You might be a careful driver. You might follow the rules, keep your distance and never touch your phone behind the wheel.
Unfortunately, you’re not the only person on the road.
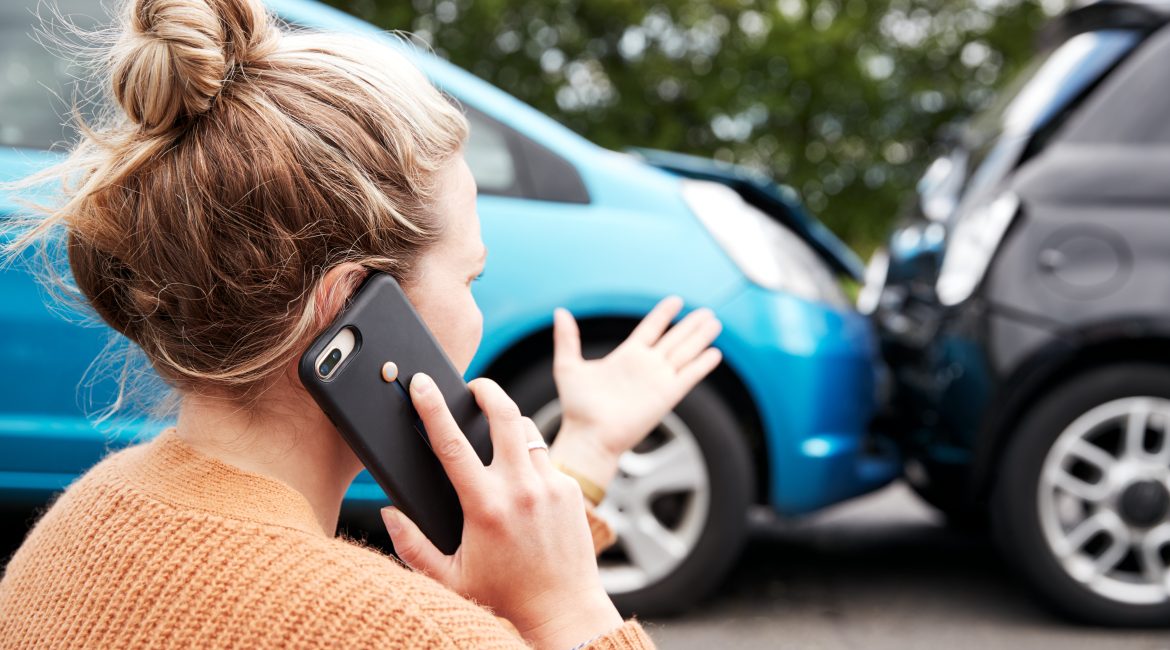
A car accident can happen in seconds, and if you don’t have car insurance, the financial headache afterwards can last a lot longer than the accident itself.
So, what actually happens if you’re involved in a car accident without insurance in South Africa?
Driving without insurance in South Africa
Here’s a stat that might make you hold the steering wheel a little tighter: the Automobile Association has estimated that only around 35% of vehicles in South Africa are insured.
That means there’s a good chance the person involved in an accident with you might not have insurance either.
And accidents themselves are expensive. According to the Road Traffic Management Corporation, the estimated cost of road crashes in South Africa was R198.3 billion in 2025.
Of course, that’s the cost across the country. What matters to you is what one accident could cost when it’s your car sitting on the side of the road.
Discover common causes for car accidents.
What happens if you have an accident without car insurance?
It depends on what happened, who was responsible and whether the other vehicle is insured.
But without your own cover, you don’t have an insurer stepping in to manage a qualifying claim for damage to your vehicle.
That can leave you dealing with repairs, recovery costs and claims against another driver yourself.
And if you’re legally liable for damage to someone else’s vehicle or property, those costs could become your responsibility too.
Discover what pictures to take when your have been in a car accident.
You could be paying for more than your own car
Imagine you’re involved in an accident that badly damages your car and another vehicle.
Without insurance, the cost isn’t necessarily limited to fixing your own bumper.
Depending on the circumstances and who is legally liable, you could potentially face costs relating to damage to another person’s vehicle or property as well.
Considering how expensive modern vehicles, parts and repairs can be, one accident can become a very expensive day out.
What if the accident wasn’t your fault?
This is where things can get frustrating.
If another driver is responsible for the accident, you may be able to recover your losses from them or their insurer.
But that doesn’t necessarily mean money lands in your account the next morning.
Liability may need to be established, the damage assessed and the claim dealt with. If the other driver is uninsured, recovering what you’re owed may become even more complicated.
Having your own insurance means you can submit a claim to your insurer for an insured event, subject to your policy terms, rather than having to navigate the entire situation on your own.
Discover who are more prone to car accidents.
What if your car is financed?
Here’s another important one.
Your car being badly damaged, written off or stolen doesn’t automatically make the finance agreement disappear.
If you financed your vehicle, you still have obligations to the finance provider under your credit agreement.
This is also why vehicle finance agreements commonly require comprehensive insurance while the vehicle is being financed.
Without adequate insurance, you could find yourself owing money on a car you can no longer use.
What does car insurance actually cover?
Not all car insurance is the same, so it’s important to understand what you’re buying.
Depending on the type of policy you choose, car insurance can provide cover for things such as:
- Accidental damage to your vehicle
- Theft or hijacking
- Damage caused by certain insured events
- Legal liability for damage you cause to someone else’s property
Exactly what’s covered will depend on your insurer, your chosen cover and your policy terms.
This is why looking at the cheapest monthly premium alone isn’t always the best way to compare car insurance. Look at what you’re actually covered for, the excess you’ll need to pay and the exclusions that apply.
What is a car insurance excess?
An excess is the amount you may need to contribute towards a claim before or as part of the insurer settling the covered loss.
The amount and circumstances in which an excess applies depend on your policy.
Before choosing car insurance, check your excess as carefully as you check your monthly premium. A cheaper premium can sometimes come with a higher excess, so you want to know what you could be expected to pay if you actually need to claim.
Is car insurance worth it?
Think about what replacing or repairing your car would do to your finances right now.
Could you comfortably pay a large repair bill? What if your car were stolen? What if it were written off? What if you were legally liable for damage to an expensive vehicle?
That’s the risk you’re taking on when you drive without insurance.
Car insurance doesn’t stop accidents, theft or bad drivers from happening. What it can do is help protect you against the financial impact of insured events when they do.
Have a plan before something happens
You don’t want the first time you think seriously about car insurance to be while you’re standing next to a damaged car.
Oneplan Car and Household Insurance gives you cover for life’s unexpected moments on the road, with different cover options so you can choose the protection that suits your needs and budget.
Take a look at your options, understand what’s covered and make sure you know what you’re paying for before you need to use it.
Your Insurance Family,